SSI deeming rules and inheritance, Digi Mart USA News: A 67-year-old woman collecting the maximum federal Supplemental Security Income (SSI) payment for 2027, which is $1,029 a month, could lose that check even though her husband, who does not receive SSI, inherited $250,000 in cash and deposited it in a savings account in his name only. She assumed her benefit was safe because she never inherited a dollar.
SSI is based on financial need, unlike Social Security retirement benefits, which are earned through payroll taxes and have no limit on assets. SSI goes only to people with very little income and very few assets.
The key rule in this situation is deeming: when an SSI recipient lives with an ineligible spouse, that spouse’s resources are treated as hers, even if she has no access to them.
Cash and bank accounts count as resources. The resource limit for a couple remains $3,000 in 2027, even though payments rose with the 3.6% cost-of-living adjustment (COLA).
By that measure, the household would be $247,000 over the limit.
The process works in two steps. Money received during a month is first treated as income for that month.
If it is still in the account on the first day of the next month, it counts as a resource. The husband’s income can also be deemed to his wife, so her check may shrink or disappear in the same month the inheritance arrives.
Social Security checks countable resources at the start of each month. If the couple holds more than $3,000 at that point, she is not eligible for SSI that month.
For example, if the inheritance arrives in March and is still there on April 1, she loses her April eligibility, regardless of whose name is on the account.
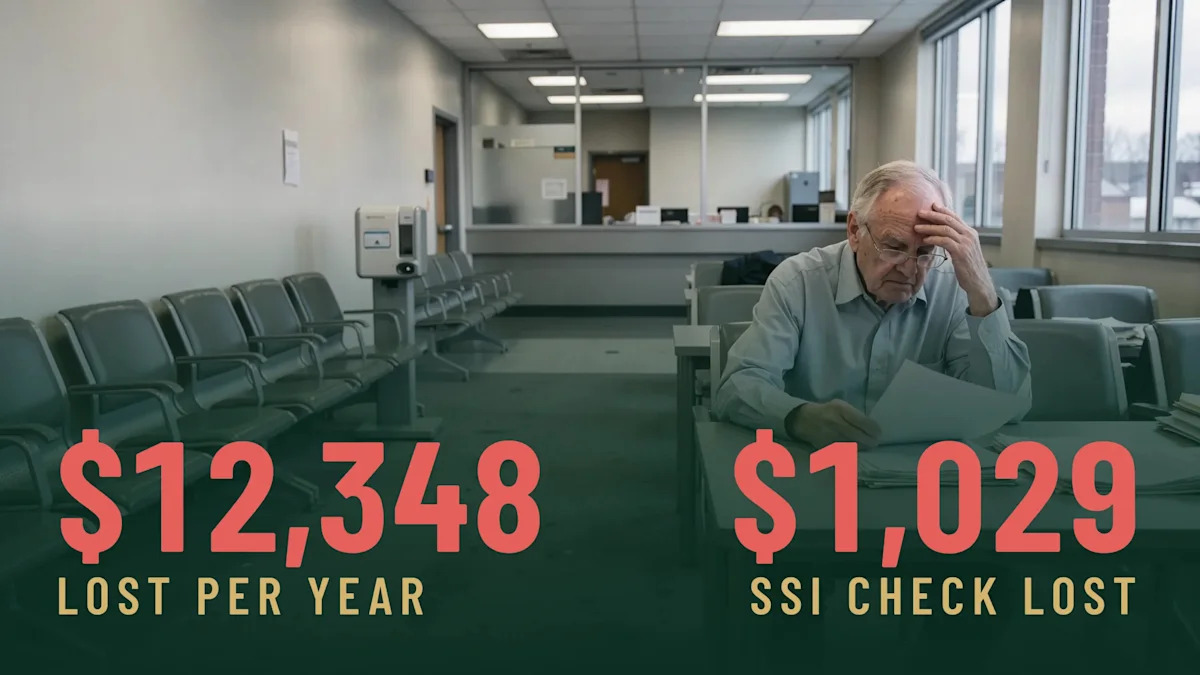
At the federal maximum, she would lose $1,029 a month, or $12,348 a year, for as long as the money remains countable. State supplements and other income can change the exact amount.
In many states, SSI eligibility also qualifies a person for Medicaid, so losing the check could affect health coverage as well.
Reporting the change promptly is important. If an inheritance is not reported, Social Security typically learns of it later and may seek repayment for every month she was paid while ineligible.
Some assets are excluded from the calculation, including the home the couple lives in, one vehicle used for transportation, household goods, and burial funds of up to $1,500 each. A non-SSI spouse’s IRAs and work pensions are also excluded.
Paying down a mortgage or replacing an old car at a fair price can convert countable cash into excluded property. Keeping receipts is advised, since spending reduces countable resources as of the first of the following month and records can show when the household fell back under $3,000.
Giving the money away is not a solution. Transferring cash to children or selling property to a relative at a discount can trigger an SSI penalty of up to 36 months if Social Security determines the transfer was made to qualify for benefits.
That rule is separate from Medicaid nursing-home coverage, which uses a different five-year look-back period.
For many couples, a $250,000 reserve could more than offset $12,348 a year in SSI, and keeping much of the money may be the right choice. The decision should be made deliberately and before the first of the month arrives.
Because state rules and each household’s mix of income and assets can change the outcome, consulting Social Security or an elder law attorney before moving any money is advisable.