France pension age increase to 64 and lessons for the UK, Digi Mart USA News: France has long been seen from the outside as a place where people retire early and well. However, recent protests have highlighted the gap between that promise and future reality.
Economists warn that France will be unable to resolve its debt crisis without tackling sky-high pension bills, and that the government must navigate a political minefield to do so. The United Kingdom faces a similar challenge.
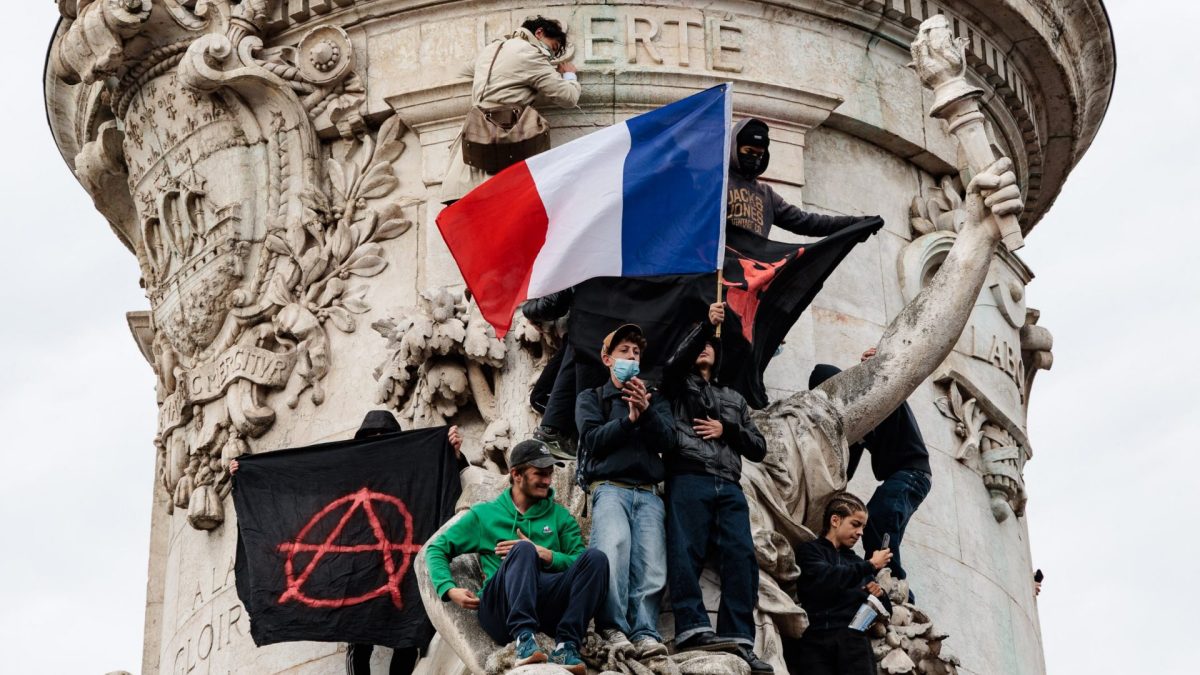
France currently spends a massive 14 per cent of its GDP on pensions, and the costs are rising. President Emmanuel Macron’s 2023 decision to curb spending by raising the retirement age from 62 to 64 sparked riots and a national strike.
Recent moves to make budget savings through cuts elsewhere, such as in healthcare, education and the civil service, have also provoked mass protests and rioting across the country.
Falling birth rates combined with rising life expectancy in France and the UK mean pensions in both countries are putting pressure on public finances. The figures and public feeling around the issue are less extreme in the UK, but the cost of supporting an ageing population remains a major concern, leading to moves to scrap the triple lock.
The two countries’ pension structures differ fundamentally, particularly in their reliance on the state. The UK uses a hybrid model anchored by a flat-rate state pension, which is backed by mandatory private and workplace pensions into which people are automatically enrolled.
The state pension is currently capped at £12,548 a year, rising to £13,036 next year, and is not meant to stand alone for most people.
In France, there is barely any reliance on private or workplace pensions, and nearly all retirement income is funnelled through mandatory public schemes. The core state pension guarantees up to 50 per cent of a worker’s average salary over the 25 years in which they earned the most.
Mandatory occupational schemes top this up to a total net replacement rate of around 72 per cent. As a result, there has been less pressure in France to invest in private pensions.
France’s pension system is cherished by its citizens, and attempts to reform it face fierce opposition. Economists have warned that unless France acts, it will struggle to end its debt crisis.
Public debt is approaching 120 per cent of GDP, raising doubts about economic stability. In the UK, public spending will be further strained next year as state pensions are set to rise by 3.9 per cent.
British debt is projected to reach around 95 per cent of GDP by the end of 2026.
Fraser Thorne, chief executive of investor relations group Edison, told The i Paper that while both countries can afford to grow old, neither can ignore the arithmetic indefinitely. “Both the UK and France have work to do,” he said, adding that “France’s position is the more acute.” He added: “What we’re seeing in both countries is the beginning of a long renegotiation between what was promised and what can actually be delivered.”
Britain’s state pension age is 66 and will rise to 67 in phases by 2028. These changes have met with some opposition but not the widespread anger seen in France.
Heidi Karjalainen, a senior research economist at the Institute for Fiscal Studies, said larger private pension pots in the UK make it easier to increase the state pension age. “If we think about the increase in the state pension age, that’s a tool governments across the world have used to try and reduce spending on the state pension,” she said.
“In France, it’s been really difficult to do that.”
Karjalainen suggested this cushion will help the UK better navigate the challenges of an ageing population and falling birth rates. The value of individual contributions to personal pension schemes has risen steadily in the UK since 2016, reaching £15.9bn in the 2024/25 financial year, up from £14.6bn a year earlier, according to the latest government figures.
“In France, if you make changes to the state pension, you’re affecting, for basically everyone, the age from which they can access their pension,” Karjalainen said. In the UK, “people can still access their private pension from 55, although that’s going to now rise to 57.” She also pointed to the time UK citizens have to prepare for changes, in contrast to France’s previous reforms.
Thorne agreed, describing France’s process as a “pointed lesson in what can happen when governments try to reset the terms of the pension contract: five prime ministers in two years, mass street protests and a reform ultimately diluted by political reality even when the economics were clear.” He acknowledged that pension reform is becoming harder everywhere “as younger generations grow more aware of what they are being asked to finance, and what they are unlikely to receive on the same terms.”
Karjalainen said cross-party agreements in both countries are now necessary to give citizens confidence that the system will remain stable. Otherwise, younger people may doubt there will be a state pension waiting for them and lose faith in the system altogether.
“You can’t have a pension system where things are just changing every parliament, because then people will lose confidence in it,” she added.