Social Security spousal benefits for divorced spouse, Digi Mart USA News: A divorced woman who turned 67 this year may be able to claim a Social Security spousal benefit based on her ex-husband’s record, according to a 24/7 Wall St. personal finance article published November 14, 2026. The article says she assumed her check would stay on hold until her ex-husband filed, a belief the publisher says could cost her more than $25,000 a year.
Under the rule described in the article, a divorced spouse can claim on an ex-spouse’s record even if he has never applied, provided the marriage lasted at least 10 years, she is at least 62, she has not remarried, and the divorce has been final for at least two years. The publisher states that the ex-spouse has no say in the claim and that the check does not reduce what he receives.
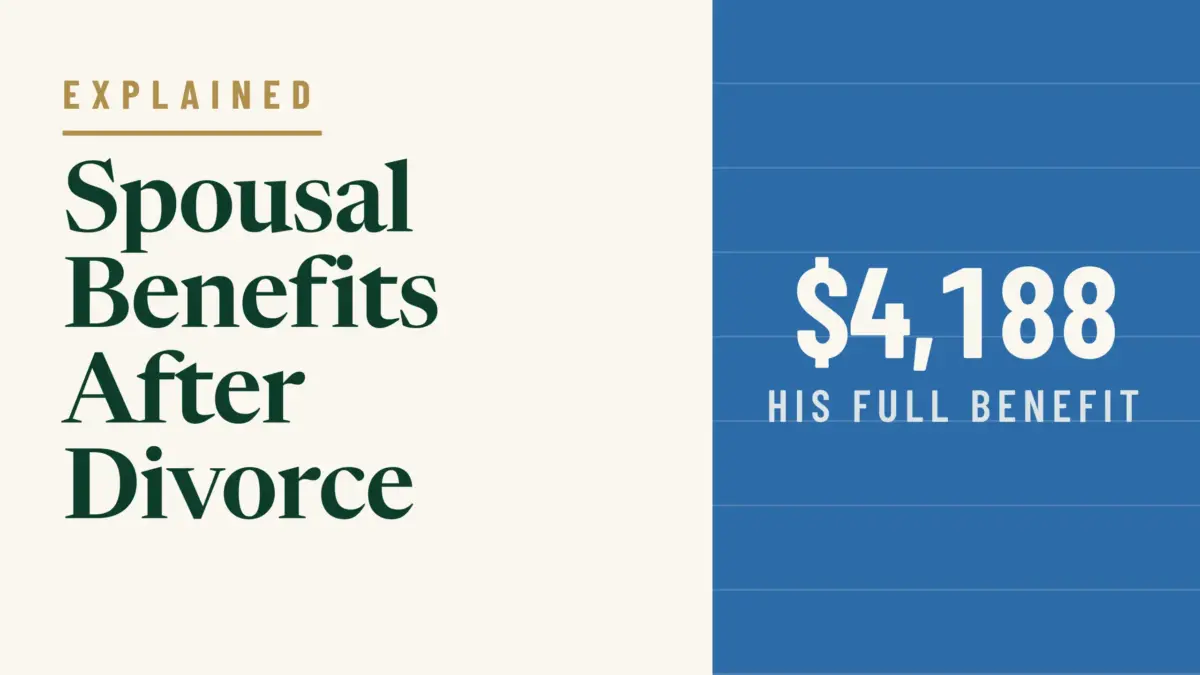
Using the article’s example of a $4,188 full retirement amount, the spousal benefit could reach up to half that figure, or $2,094 a month ($25,128 a year). The article notes that spousal benefits do not increase after full retirement age, so the ex-spouse’s delayed filing or extra credits to age 70 would not raise her spousal check.
The article also says Social Security can pay benefits retroactively for up to six months, but not for months before she became eligible. It adds that she should compare her spousal estimate with her own retirement benefit, since Social Security pays the higher amount.
The publisher says the 3.6% cost-of-living adjustment for 2027 would apply to whichever benefit she receives.
The article further notes that if her ex-spouse dies first, a surviving ex-spouse may be eligible for survivor benefits of up to 100% of the late worker’s benefit once she reaches the qualifying age. Taxes and Medicare premiums may also apply: the article cites 2026 figures, including a $25,000 single-filer threshold for taxation of Social Security income and a $202.90 standard monthly Part B premium with higher premiums above income limits.
These details are attributed to the publisher’s reporting and should be confirmed with the Social Security Administration.