Australian sharemarket weekly gains despite Wall Street AI stock selloff, Digi Mart USA News (Australia): Australian shares limped across the finish line on Friday but notched a second straight week of gains, despite facing a slew of domestic and global risks.
The S&P/ASX 200 fell 44.3 points, or 0.49 per cent, to 9020.8, while the broader All Ordinaries lost 60.5 points, or 0.66 per cent, to 9144.7. The benchmark index was still up 1.2 per cent since Monday and has risen for five of the past six weeks, despite the Reserve Bank raising the official cash rate to 4.85 per cent on Tuesday, its highest level since 2008.
The Australian dollar was buying 69 US cents, down from 70.09 US cents on Thursday at 5pm. Mining stocks eased from Thursday’s surge, tracking tumbling US technology stocks as traders weighed the likely impact of the US midterm elections on the artificial intelligence build-out that has supported 2026 stock prices and driven Wall Street’s bull market.
Miners BHP, Rio Tinto and Fortescue fell 2.34 per cent, 2.03 per cent and 2 per cent respectively. Gold miners also slumped, with Northern Star sliding 1.12 per cent and Evolution down 2.64 per cent.
Technology stocks followed the meltdown on the Nasdaq composite, with Megaport initially tumbling 9.5 per cent before finishing down 3.89 per cent and Codan closing 2.9 per cent lower. Xero and WiseTech, Australia’s most valuable tech company, retreated by less than 1 per cent.
Most financial stocks helped lift the market, with small gains across the board. Commonwealth Bank added 0.73 per cent, Westpac rose 1.06 per cent, National Australia Bank jumped 2.67 per cent and ANZ added 0.6 per cent.
Macquarie Group slumped 3.69 per cent after financial regulator APRA imposed a $100 million capital penalty, saying the firm breached capital requirements for its non-bank businesses. The wealth giant also reported half-year profits of $2.48 billion.
Energy stocks were largely stable as oil prices advanced overnight after a steep drop in the previous session.
In the United States, the S&P 500 fell 4.4 per cent, its worst drop since President Donald Trump shook markets worldwide in April 2025 with his "Liberation Day" tariffs. The wipeout more than erased the previous day’s gain, which had been the market’s best in three months.
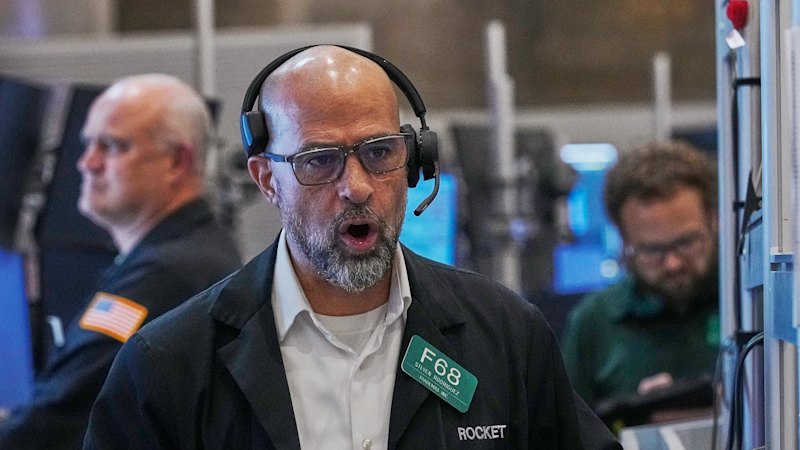
The Dow Jones Industrial Average dropped more than 1,800 points and the Nasdaq composite tumbled 5.5 per cent. About US$3.2 trillion (A$4.6 trillion) was wiped off Wall Street.
AI stocks worldwide came under pressure as worries grew about possible moratoriums on data centres following Democratic victories in the US midterm elections. Trump blamed Democrats for heavy losses in Americans’ 401(k) retirement portfolios, a system similar to Australia’s superannuation, as the selloff deepened after his Republican Party suffered widespread losses.
"Such a sad thing to watch!" the president said in a post on his Truth Social platform after the close. "It took us so much work to get us to a level that no one has ever seen before, and then this."
The nationwide Democratic victories raised the possibility that governments could force pauses in construction of more data centres, which would mean fewer purchases of AI chips and less demand for electricity and other products tied to the AI boom that has been driving much of the US economy’s growth. Nvidia fell 9.3 per cent and was by far the heaviest weight on the S&P 500, a day after dropping 3.2 per cent.
Advanced Micro Devices tumbled 17.3 per cent, and CoreWeave, which rents access to AI chips to customers over the cloud, fell 9.8 per cent.
AI chip stocks are among Wall Street’s most influential because they have become some of its largest. Over the long term, stock prices tend to follow corporate profits and interest rates, depending on those factors far more than on who controls what in Washington.