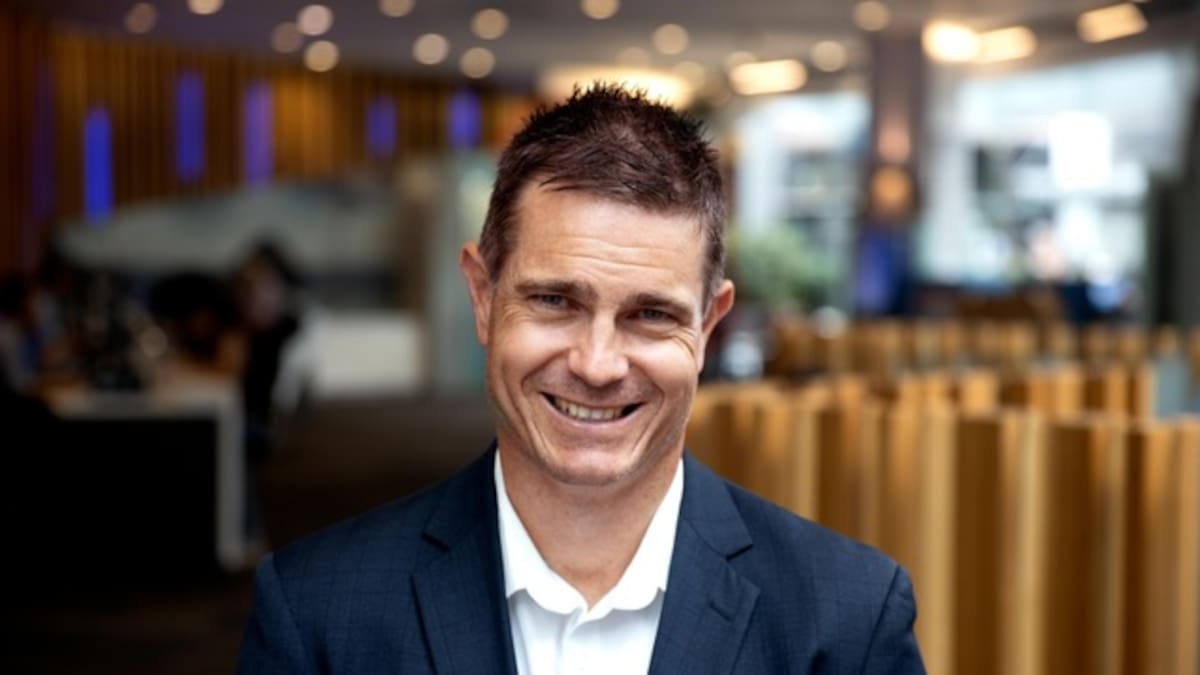
ANZ New Zealand house price recovery outlook, Digi Mart USA News (New Zealand): ANZ New Zealand chief executive Ben Kelleher says a recovery in house prices is still some way off. He said prices, which the bank expects to fall by 2% this calendar year, may have bottomed and are likely to remain soft in 2027.
“It feels like it’s hitting the bottom of the curve but it has been low for a while,” Kelleher told the New Zealand Herald at the release of the bank’s annual result. “I don’t expect it to be off to the races any time soon,” said Kelleher, who took over from outgoing chief executive Antonia Watson in October.
ANZ, the country’s biggest bank with about 30% of the market, reported a cash net profit of $2.306 billion for the year ended September 30, down 3% from the previous year. The bank’s statutory net profit was $2.359 billion, down 7%, driven by lower gains from economic hedges and higher expenses.
Kelleher said the economy over the year had been uneven. “I’ve likened it to an economy that’s been bunny hopping through the year, where we’ve had export-facing parts of the economy doing better,” he said.
He pointed to better commodity prices, the Fonterra capital return, a favorable exchange rate and a tourism sector that has been bouncing back.
“But at the same time, we’re also seeing households and businesses continue to do it tough in some areas,” Kelleher said. “There are definitely pockets of strength, but there are also pockets of weakness out there.”
The bank’s net interest margin, a key measure of a bank’s performance, eased by seven basis points to 2.52%, reflecting increased competition. “There is really strong competition between the existing banks and obviously you’ve got new entrants coming in, like Revolut,” Kelleher said.
“Our view is competition is great for customers, and we say bring it on.”
Lending and deposits grew 3% and 4% respectively, with momentum in smaller business lending gaining 9.1%. Home lending was up 4.4% amid a soft housing market and tough competition between banks.
Agri lending increased 2.8% to $15.8 billion, lifting market share as ANZ remained New Zealand’s largest agricultural lender.
ANZ said its agri deposits were up 15.4%, helped by high commodity prices and the Fonterra capital return. Delinquency, meaning borrowers who are 90 days past their due date for repayments, was falling, but there was a small increase in “hardship,” where borrowers are concerned about missing a payment in the future.
The bank’s annual report showed former chief executive Antonia Watson was paid A$2.59 million (US$3.2 million) in 2026, down from A$2.7 million (US$3.34 million) in 2025. Her total statutory remuneration, which includes vested grants, came to A$5.07 million (US$7.05 million).
In May, ANZ customers won a class action against the bank on the ground that it had breached the Credit Contracts and Consumer Finance Act (CCCFA) in the mid to late 2010s. A coding error in one of ANZ’s loan calculators led it to charge about 17,000 customers the wrong amount of interest.
ANZ New Zealand has appealed the High Court decision granting summary judgment against the bank to the representative plaintiffs.
Expenses increased 9%, including the impact of a provision. Excluding the provision, expense growth was 3%.
ANZ said its cash profit would have been up 1% excluding the class action provision.
The bank said many home loan customers continued to benefit from earlier falls in fixed mortgage rates, with about 85% of fixed loans below 5%. “Many have been prudent with around 47% of home loan customers at least six months ahead on repayments and almost half of them having a savings buffer of $5000 or more,” Kelleher said.
ANZ Group, the parent, reported a full-year cash profit of A$7.59 billion (US$9.38 billion), in line with market expectations. The bank declared a final dividend of A83 cents (US$1.03) a share, bringing the total dividend to A$1.66 (US$2.05), unchanged from the previous year.