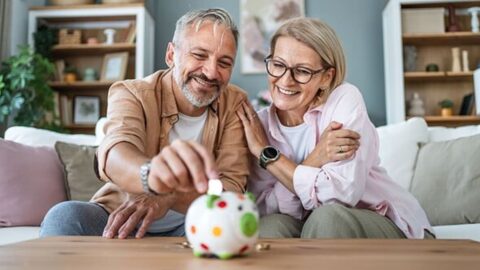
Medicaid joint bank account rules when adding a granddaughter to a grandparent’s savings account, Digi Mart USA News: A grandmother who adds her teenage granddaughter to her $60,000 savings account to help her start building wealth may create unexpected Medicaid complications, according to a personal finance report published by 24/7 Wall St. The article describes a scenario inspired by a Fortune report from October 18 that Gen Z starts building wealth at 19 on average.
The publisher explains that if the grandmother later applies for Medicaid to fund nursing facility care, states using Supplemental Security Income-style joint-account rules can begin with a presumption that the full $60,000 belongs to her. Under the SSI rule cited in the report, when only one applicant sits on an account, funds are presumed to belong to that individual.
Adding the granddaughter’s name does not automatically split the money.
That presumption can be overcome, the article says, through a written statement from the grandmother and supporting statements from other account holders explaining ownership, deposits, withdrawals and how the money was spent, backed by account records. The report notes that states can apply their own Medicaid resource rules, so the presumption and the proof required may differ.
The article warns of a separate risk: federal Medicaid law can treat action by another joint owner that reduces the grandmother’s ownership or control as a transfer by her. If the granddaughter withdraws money for herself, such as for tuition, rent or a trip, that withdrawal could be treated as a gift by the grandmother.
During the five-year look-back period for long-term care Medicaid, the report says transfers may be scrutinised and can lead to a penalty period whose length depends on the transfer size and the state’s nursing home costs.
According to the publisher, Medicare generally covers only short skilled nursing stays after a hospital admission and would not cover this gap. Withdrawals that pay the grandmother’s own expenses, such as prescriptions, property taxes or groceries, are not treated as gifts, the article says.
The report suggests families consider keeping the account in the grandparent’s name, making documented early gifts, or using a payable-on-death designation, which names a beneficiary without giving access during the owner’s lifetime. The article is a publisher analysis and was not independently verified.